IRDAI Insurance Reforms 2026: Proposed Commission Caps
Explore IRDAI’s proposed insurance commission caps, existing payouts and sales reforms, ...
25 September 2026
Finnovate’s editorial team researches and creates financial content using trusted sources, regulatory references and inputs from subject experts.
Last reviewed: 16 October 2026
If you pay health insurance premiums or eligible medical expenses for your parents, you may be able to claim a deduction under Section 80D of the Income-tax Act, 1961, when using the old tax regime for FY 2025-26 (AY 2026-27). This guide covers the limits for parents and senior citizens, when medical bills qualify, payment rules, and why the deduction is not available in the new tax regime. It also explains the corresponding provision under the Income-tax Act, 2025, which applies from Tax Year 2026-27.
Quick Answer: Section 80D for parents and senior citizens (FY 2025-26)
Is Section 80D allowed in the new tax regime? No. For FY 2025-26, the deduction is available only under the old tax regime, subject to eligibility. It is not permitted under the new tax regime (Section 115BAC). The corresponding deduction in Section 126 of the Income-tax Act, 2025 is also subject to the applicable tax-regime rules.
| Who is covered | Deduction limit | What qualifies |
|---|---|---|
| Parents below 60 (premium) | Up to ₹25,000 | Health insurance premium (non-cash payment only) |
| Resident parents aged 60 or above (premium) | Up to ₹50,000 | Eligible premium paid without cash; at least one parent must meet the resident senior-citizen definition |
| Resident parents aged 60 or above (medical expenditure) | Up to ₹50,000 | Qualifying medical expenditure for a resident senior citizen for whom no health insurance premium has been paid |
| Preventive health check-ups (self/family/parents) | Up to ₹5,000 | Within the overall 80D cap; cash payment allowed |
Limits apply per financial year and within the old tax regime. The maximum combined deduction can reach ₹1,00,000 where both the self/family category and the parents category qualify for the ₹50,000 limits. For Section 80D, a senior citizen must be aged 60 or more and resident in India in the relevant year.
| Covered Group | Limit |
|---|---|
| Parents below 60 (premium) | Up to Rs 25,000 |
| Resident parents aged 60 or above (premium) | Up to ₹50,000 |
| Resident parents aged 60 or above (eligible medical expenditure; no premium paid for that parent) | Up to ₹50,000 |
Preventive health check-up up to Rs 5,000 is included within the relevant cap. It is not an additional allowance on top of the premium limit. Premiums must be paid via non-cash modes; only preventive check-up expenses may be paid in cash.
| Scenario | Self/Family Limit | Parents Limit | Total |
|---|---|---|---|
| Self below 60; Parents below 60 | Rs 25,000 | Rs 25,000 | Rs 50,000 |
| Self below 60; Resident parents aged 60+ | Rs 25,000 | Rs 50,000 | Rs 75,000 |
| Resident self aged 60+; Parents below 60 | Rs 50,000 | Rs 25,000 | Rs 75,000 |
| Resident self aged 60+; Resident parents aged 60+ | Rs 50,000 | Rs 50,000 | Rs 1,00,000 |
These are maximum eligible deductions, not guaranteed tax savings. A ₹50,000 deduction reduces taxable income by up to ₹50,000; it does not directly reduce tax payable by ₹50,000. The actual saving depends on the applicable tax rate, taxable income and eligibility under the old regime. The senior-citizen limits in the matrix assume the relevant insured person is resident in India.
If you pay medical expenses for a resident parent aged 60 or above, you may claim qualifying expenditure of up to ₹50,000 under the parents' category, provided no amount has been paid to obtain or maintain health insurance for that particular parent. This condition is person-specific. For example, a premium paid for an insured father does not, by itself, prevent a claim for eligible medical expenses of an uninsured resident senior-citizen mother. The combined deduction for both parents still cannot exceed ₹50,000.
Qualifying expenses may include consultations, diagnostics, medicines and hospital treatment. Pay by a non-cash mode such as UPI, card, cheque or bank transfer. Keep itemised bills, evidence of payment and documents identifying the patient. The deduction is for actual qualifying amounts paid, not a flat allowance.
NRI note: A non-resident Indian taxpayer may claim the deduction for eligible health insurance premiums under the old tax regime, subject to the policy and payment conditions. However, the ₹50,000 senior-citizen limit depends on the insured person's Indian residency, not just their age. If both parents are non-resident, the normal ₹25,000 parents' premium limit generally applies even if they are aged 60 or above. The medical-expenditure deduction is available only for a resident senior citizen; it cannot be claimed for a non-resident parent. See the Income Tax Department's Section 80D and Section 2(100) of the 2025 Act.
Up to Rs 5,000 for preventive health check-ups (for self, family, and parents combined) can be claimed within the applicable 80D caps. Unlike premiums, this portion may be paid in cash. It is not an additional allowance over and above the Rs 25,000 or Rs 50,000 limits; it forms part of them.
Documentation summary: Retain premium receipts, policy details, insurer information and payment records. For medical expenditure, keep itemised bills identifying the resident senior-citizen patient and the non-cash payment records. Keep preventive check-up receipts even when paid in cash. For a multi-year policy, retain documents showing the full coverage period and premium paid.
Under the new tax regime for FY 2025-26 (Section 115BAC), Section 80D cannot be claimed. While the new regime allows certain specifically permitted deductions, including eligible employer NPS contributions under Section 80CCD(2), these exceptions do not include Section 80D. The equivalent health-insurance deduction under Section 126 of the 2025 Act is likewise not available under the new regime applicable to Tax Year 2026-27.
If Section 80D and other deductions are substantial, compare your total tax liability under both regimes rather than deciding from the Section 80D amount alone. For AY 2026-27, taxpayers without business or professional income generally exercise the old-regime option in a timely filed ITR. Eligible taxpayers with business or professional income must follow the separate Form 10-IEA procedure and the applicable due-date and switching restrictions. See the Income Tax Department's Form 10-IEA guidance.
Deciding between the old and new tax regime, calculating the right deduction claim across self, family, and parents, and structuring health cover tax-efficiently are all part of a broader tax planning review. Finnovate's tax planning advisory covers regime comparison, deduction optimisation, and ITR strategy for individuals and families.
Yes. The Income Tax Act, 1961 distinguishes "dependent children" from "parents." Dependency is not a stated condition for the parents' deduction under Section 80D. The deduction applies as long as you pay the premium and the other conditions are met.
Yes, if the parent is aged 60 or above, resident in India, and no amount has been paid to effect or maintain health insurance for that parent. Eligible consultations, tests, medicines and hospital bills may be claimed up to ₹50,000 within the parents' combined cap, provided payment is non-cash and supporting bills are retained. A different parent being insured does not automatically remove this eligibility.
Insurance premiums must be paid via non-cash modes only. Cash payments for premiums disqualify the claim entirely. The only exception is preventive health check-up expenses, which may be paid in cash up to Rs 5,000 within the overall 80D cap.
No. Section 80D is a Chapter VI-A deduction and is not available under the new tax regime (Section 115BAC) for FY 2025-26. If Section 80D deductions are significant for your tax calculation, the old tax regime may produce a lower overall liability. Please consult a qualified tax adviser before making your regime choice.
Yes. Eligible CGHS or other notified scheme contributions may qualify under Section 80D, but they form part of the self/family category under Section 80D(2)(a), not the separate parents' deduction under Section 80D(2)(b).
Yes. A non-resident taxpayer may claim eligible health insurance premiums under the old regime, subject to the approved insurance and payment conditions. However, to qualify for the enhanced ₹50,000 senior-citizen limit, the insured person must be aged 60 or more and resident in India. For non-resident parents aged 60 or above, the standard ₹25,000 parents' premium limit generally applies if the premium is otherwise eligible. Medical expenditure for a non-resident parent does not qualify for the senior-citizen medical-expense deduction.
From 1 April 2026, the health-insurance deduction appears as Section 126 of the Income-tax Act, 2025. The principal ₹25,000, ₹50,000 and ₹5,000 limits are retained. Returns for FY 2025-26 (AY 2026-27) still use the 1961 Act and Section 80D; Section 126 applies to Tax Year 2026-27 onwards. The old-versus-new tax regime restriction continues to matter.
Disclaimer: This article is for general information and educational purposes only and is not personalised tax or investment advice. Section 80D references relate to FY 2025-26 (AY 2026-27), while Section 126 of the Income-tax Act, 2025 applies from Tax Year 2026-27. Eligibility, insurer approval, residency, medical-expense conditions and tax-regime options depend on individual circumstances. Tax rules may change. Please consult a qualified Chartered Accountant or tax adviser before claiming deductions or choosing a tax regime. Finnovate Financial Services Pvt Ltd. | SEBI RIA Registration No: INA000013518.
No spam. Only new posts, simple explainers, and practical money checklists for busy professionals.
Finnovate is a SEBI-registered financial planning firm that helps professionals bring structure and purpose to their money. Over 3,500+ families have trusted our disciplined process to plan their goals - safely, surely, and swiftly.
Our team constantly tracks market trends, policy changes, and investment opportunities like the ones featured in this Weekly Capsule - to help you make informed, confident financial decisions.
Learn more about our approach and how we work with you:
No comments yet. Start the conversation. What would you add?
No spam. Only new posts, simple explainers, and practical money checklists.
You may also like
Explore IRDAI’s proposed insurance commission caps, existing payouts and sales reforms, ...
Indian banks earned over ₹20,000 crore distributing insurance in FY26. HDFC Bank led at ...
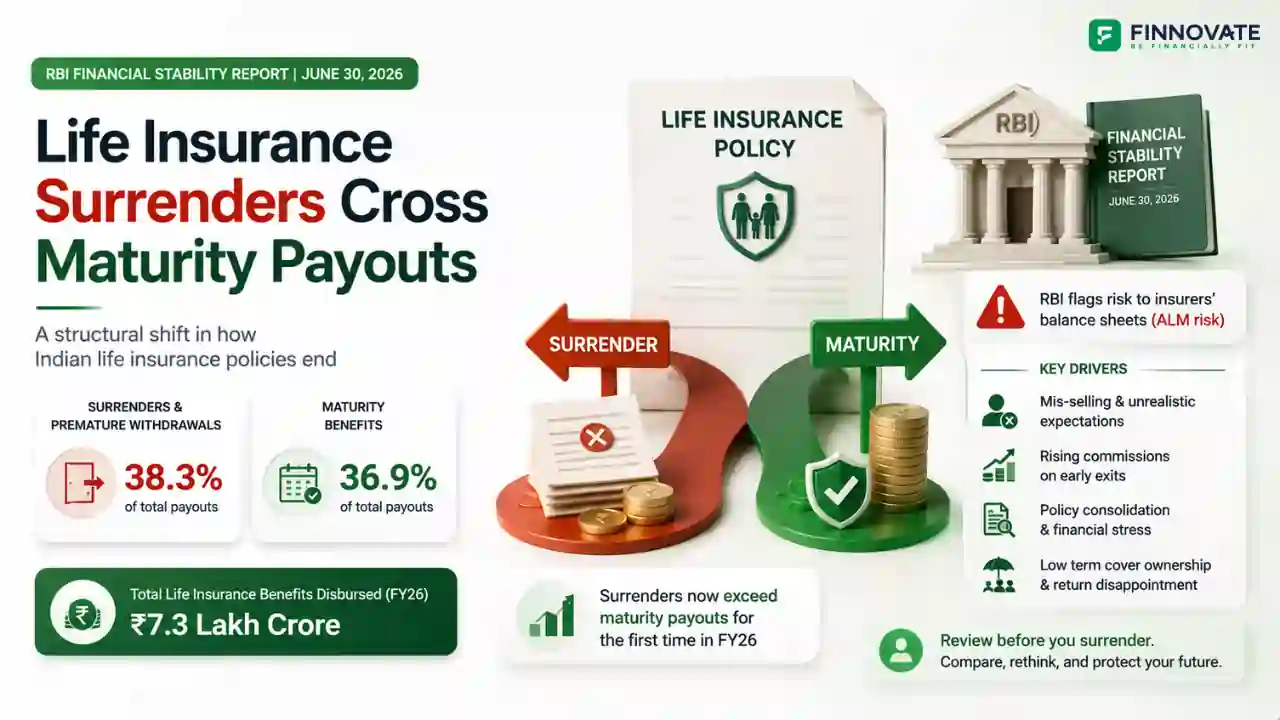
Surrenders made up 38.3% of life insurance payouts in FY26, ahead of maturity benefits at ...
India's 2025 insurance law passed by Parliament didn't extend open architecture to individ...
Popular now
Learn how to easily download your NSDL CAS Statement in PDF format with our step-by-step g...
Looking for the best financial freedom books? Here’s a handpicked 2026 reading list with...
Learn what SIF investment means in India, SEBI rules, Rs 10 lakh minimum investment, avail...
Clear guide to mutual fund taxation in India for FY 2025–26 after July 2024 changes: equ...